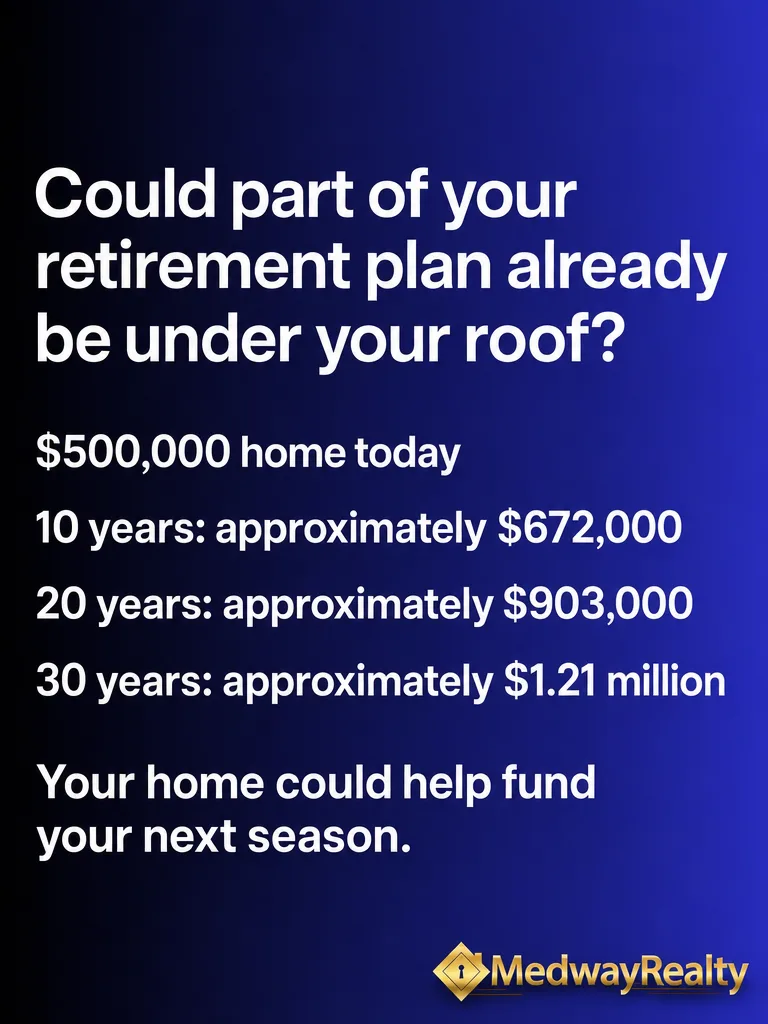
🏡 Could part of your retirement plan already be under your roof?
By Kim Donahue
I saw a graphic today showing that a $1 million investment portfolio could support a $40,000 first-year withdrawal using the familiar 4% retirement guideline.
It made me think: Are we giving our real estate the same attention as our retirement accounts?
Let's look at a $500,000 home with an illustrative 3% annual appreciation rate:
- 📍 Today: $500,000
- 📍 In 10 years: approximately $672,000
- 📍 In 20 years: approximately $903,000
- 📍 In 30 years: approximately $1.21 million
That's the power of compounding over time. And as you pay down your mortgage principal, you can build additional equity.
But here's where planning matters: A home's value and money available to spend are two different things.
For example, imagine selling a mortgage-free home for $900,000 and purchasing your next home for $500,000. That leaves a $400,000 difference BEFORE selling expenses, purchase costs, moving expenses, and any applicable taxes.
If your actual remaining proceeds were $350,000 and you invested them, a 4% first-year withdrawal would equal $14,000—about $1,167 per month—to supplement other retirement income.
Your home could help create options: right-sizing, relocating closer to family, or freeing up funds for your next chapter.
The starting point? Buy within your budget, understand the full ownership costs, and consider how the property fits your long-term life.
What role could your home play in YOUR next season?
If you're considering selling, downsizing, or right-sizing in Sarasota, Manatee, or Charlotte County, let's look at your real estate numbers together. Your financial advisor can help connect them to your retirement plan.
📩 Message me "TRANSITION."
Kim Donahue | Medway Realty
Your Realtor with a Heart to Serve.
Examples are illustrative. Appreciation is not guaranteed, property values can decline, and the 4% guideline does not guarantee sustainable retirement income.